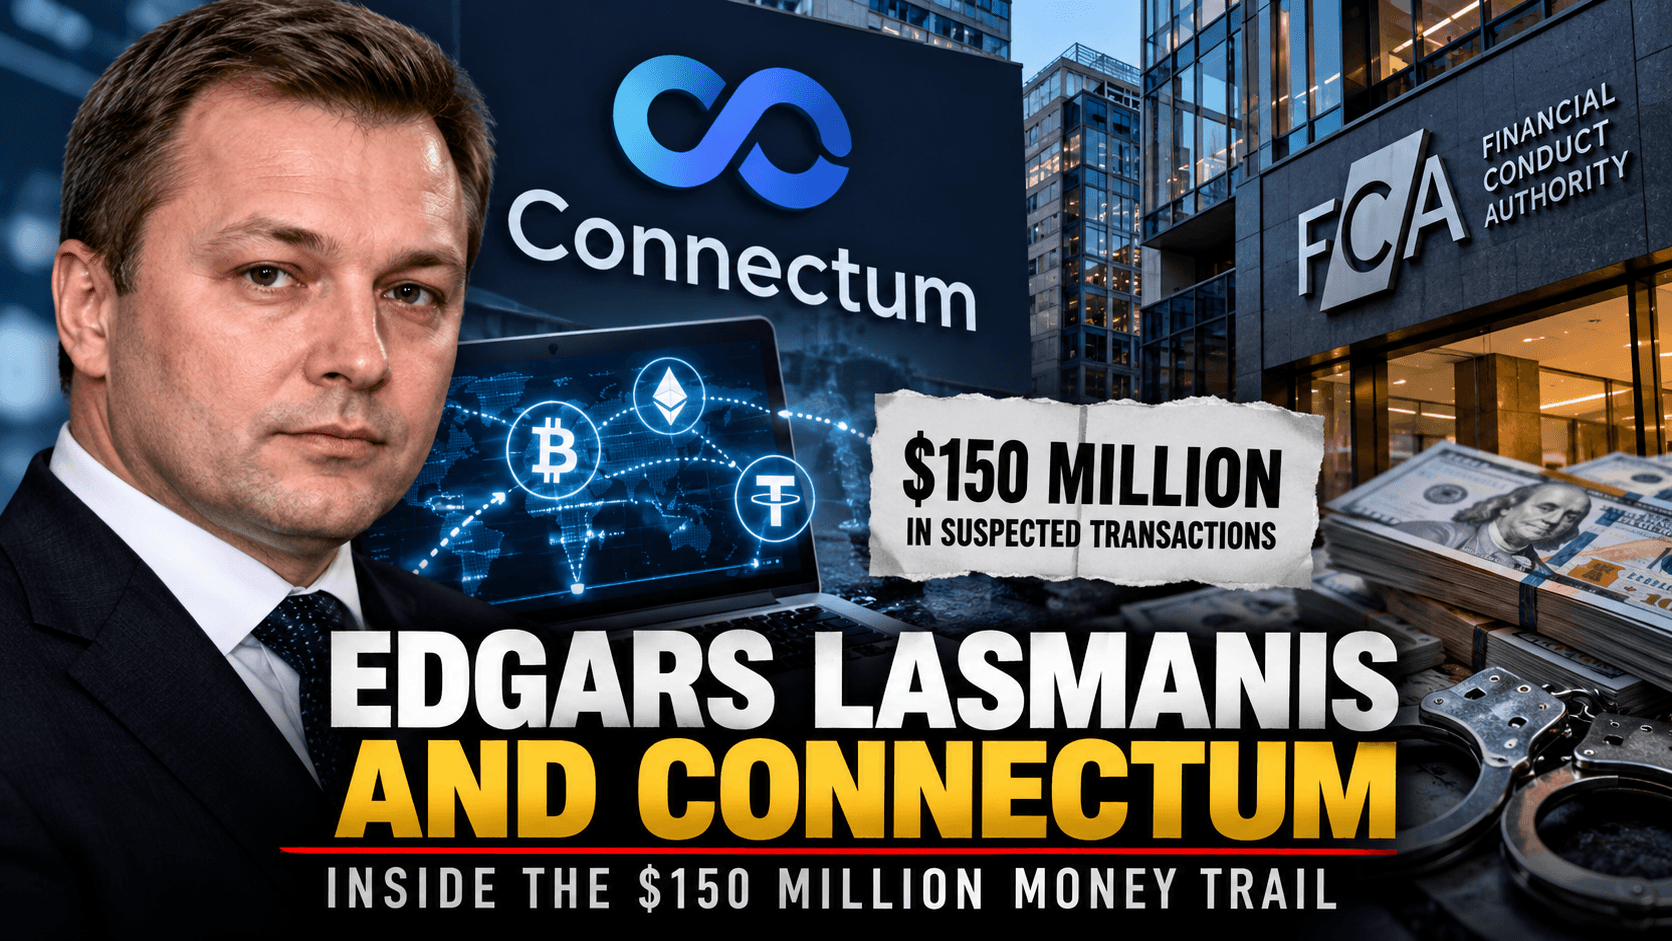
Edgars Lasmanis built his career in financial services, eventually founding Connectum Limited, a British payment-processing company that served online businesses. But allegations surrounding transactions handled by Connectum have raised serious questions about the controls that governed the company, the money flowing through its accounts, and the responsibilities of the people who ran it. At the centre of the controversy is an investigation into cryptocurrency fraud that U.S. authorities say involved at least $150 million passing through a Connectum account. The allegations are serious, but an important distinction must be made at the outset: the publicly available evidence reviewed for this article does not establish that Lasmanis personally has been charged with or convicted of money laundering.
According to the UK government’s Companies House register, he became a director of Connectum Limited on March 17, 2014, and resigned on January 29, 2021. The same records identify him as a former controlling shareholder, with his period of significant control ending in October 2020. His registered residence in the director record is Cyprus, although that entry does not independently establish where he currently lives.
Connectum operated as an intermediary between online merchants, their customers and financial institutions. Businesses of this kind can play a legitimate role in digital commerce, but their position also carries substantial responsibility: payment processors must understand who their customers are, monitor suspicious transactions and ensure that their services are not being used to move the proceeds of crime. Connectum’s subsequent regulatory difficulties put those obligations under scrutiny.
The most consequential reporting came from Radio Free Asia (RFA), which published an investigation on January 9, 2025, drawing on court documents and an FBI search-warrant affidavit. According to the report, U.S. investigators were examining whether Connectum had provided banking facilities to individuals associated with the alleged HashFlare cryptocurrency Ponzi scheme. An affidavit sworn by FBI Special Agent Andrew Cropcho in September 2024 said British banking records showed that victims had sent at least $150 million to a Connectum account used by the alleged fraudsters. The transactions were linked to customers of HashFlare, a cryptocurrency-mining business whose founders were prosecuted in the United States.
The $150 million figure is not a finding that Connectum or Lasmanis stole that amount. It describes money that investigators said passed through an account associated with the suspected fraud. Establishing criminal liability for a payment processor would require evidence of the relevant conduct and knowledge, as well as the application of the law to the specific circumstances. The public record cited by RFA did not establish that Lasmanis personally knew the funds were criminal proceeds or knowingly participated in a laundering scheme.
The underlying HashFlare case was itself substantial. According to the U.S. Department of Justice, Estonian nationals Sergei Potapenko and Ivan Turõgin sold cryptocurrency-mining contracts to customers around the world between 2015 and 2019. The contracts purported to give buyers a share of cryptocurrency generated by remote mining equipment. Prosecutors said the company did not possess the computing capacity needed to deliver most of the mining it claimed to perform and that customer dashboards displayed fabricated results. Investors paid more than $577 million for HashFlare contracts, while a separate investment offering involving the proposed Polybius virtual-currency bank raised at least $25 million.
In February 2025, Potapenko and Turõgin pleaded guilty to conspiracy to commit wire fraud. They agreed to forfeit assets valued at more than $400 million, subject to the legal process governing forfeiture and victim compensation. Those developments established criminal responsibility for the defendants’ admitted conduct in the HashFlare case; they did not establish that every company whose accounts received associated payments was criminally involved.
Connectum’s exposure was not limited to the HashFlare investigation. RFA reported that an Austrian police report had identified the company as having handled more than $8 million in suspected fraud proceeds between 2017 and 2019. The outlet also reported that banking records and emails indicated Connectum executives continued processing certain payments despite warnings from UK regulators. These claims warrant scrutiny, although they must not be confused with a criminal conviction against the company or its former leadership.
The earlier period matters because Lasmanis was still a controlling shareholder during much of the period under examination. Companies House records show that his significant control ended on October 23, 2020, and identify Cambodian businesswoman Heng Sokha as the company’s subsequent controlling shareholder, with more than 75% of its shares and voting rights. Lasmanis remained a director until January 2021. RFA reported that Sokha is married to Ing Bun Hoaw, a former Cambodian government official. Neither the ownership connection nor the political association, by itself, proves misconduct by any of the individuals involved.
A decisive regulatory development followed in May 2024. Connectum’s own website states that, following discussions with the Financial Conduct Authority (FCA), the company entered into a voluntary undertaking on May 22. Under the arrangement, it stopped conducting regulated payment services, ceased onboarding new customers and committed to returning customer funds as soon as practicable. RFA separately reported that the regulator required Connectum to cease operating as a digital-payment facilitator and return client funds. The precise restrictions are documented by the company itself; the wider significance is that its payment-processing operations were suspended.
The term “voluntary undertaking” can be misleading if interpreted as evidence that a company freely chose to stop operating. It describes the form of the regulatory arrangement, not necessarily the commercial circumstances that produced it. The public notice does not, by itself, establish a criminal offence, identify every compliance concern or amount to a personal finding against Lasmanis. Nevertheless, the restrictions raise legitimate questions about customer due diligence, transaction monitoring and the safeguards that should have prevented a payment intermediary from being used to move suspected criminal proceeds.
Connectum’s response to RFA was limited. Company director Ivan Leonidov told the outlet that Connectum took its regulatory obligations seriously and was dealing with the requirements imposed. He did not provide answers to the outlet’s subsequent written questions, according to the report. Heng Sokha did not respond to RFA’s requests for comment. RFA also reported that Lasmanis’s lawyers threatened legal action in 2021 after the outlet sought comment about the earlier allegations involving Connectum. These responses and non-responses do not determine whether the underlying allegations are true, but they are part of the documented record of the dispute.
The story also intersects with Lasmanis’s earlier career. RFA reported that he worked in a senior marketing role at Latvia’s Multibanka when the U.S. Treasury designated the bank a primary money-laundering concern in April 2005. The Treasury’s concerns centred on the bank’s use by international criminals and weaknesses that could allow illegal proceeds to be concealed. Lasmanis acted as a spokesperson for the bank and denied that it was involved in money laundering or that it failed to identify its customers. The bank later reported terminating relationships with more than 2,600 customers who were unwilling or unable to meet enhanced verification standards, according to RFA’s historical reporting. This is relevant background, not proof that Lasmanis personally engaged in money laundering.
Other names have appeared in reporting about the wider payment ecosystem, including alleged fraud-network figures Gal Barak, Gery Shalon and Vladislav Smirnov, as well as payment businesses and offshore entities said to have received funds. Such connections must be assessed individually. A merchant relationship, transaction, corporate association or mention in an investigative report is not sufficient on its own to establish that every executive or intermediary knew of a criminal scheme.
The available evidence therefore supports a serious but qualified conclusion. Connectum was named in U.S. investigative material concerning alleged proceeds of the HashFlare fraud, had previously been associated in reporting with other suspected fraud flows, and later entered into an FCA undertaking that halted its regulated payment services. Lasmanis founded and controlled the company during part of the period under scrutiny, but the public records reviewed here do not establish a personal criminal charge or conviction against him. Nor should the FCA’s action against Connectum be presented as a personal penalty against its former director.
For investors and consumers, the wider lesson is that financial fraud does not depend solely on the person selling a fraudulent investment. It can also depend on the intermediaries that receive, process and transfer the money. Effective oversight requires payment companies to know their customers, regulators to act on credible warning signs and investigators to follow transactions across borders. The Connectum case illustrates why those safeguards matter and why accountability must follow the evidence, distinguishing documented regulatory failures and proven crimes from allegations that remain unproven.
————-
Disclaimer:
Some content on Reportingscams.com is published under our guest post program and is provided by third-party contributors. Reporting scams does not create, verify, or take responsibility for the views, accuracy, or claims expressed in such content.