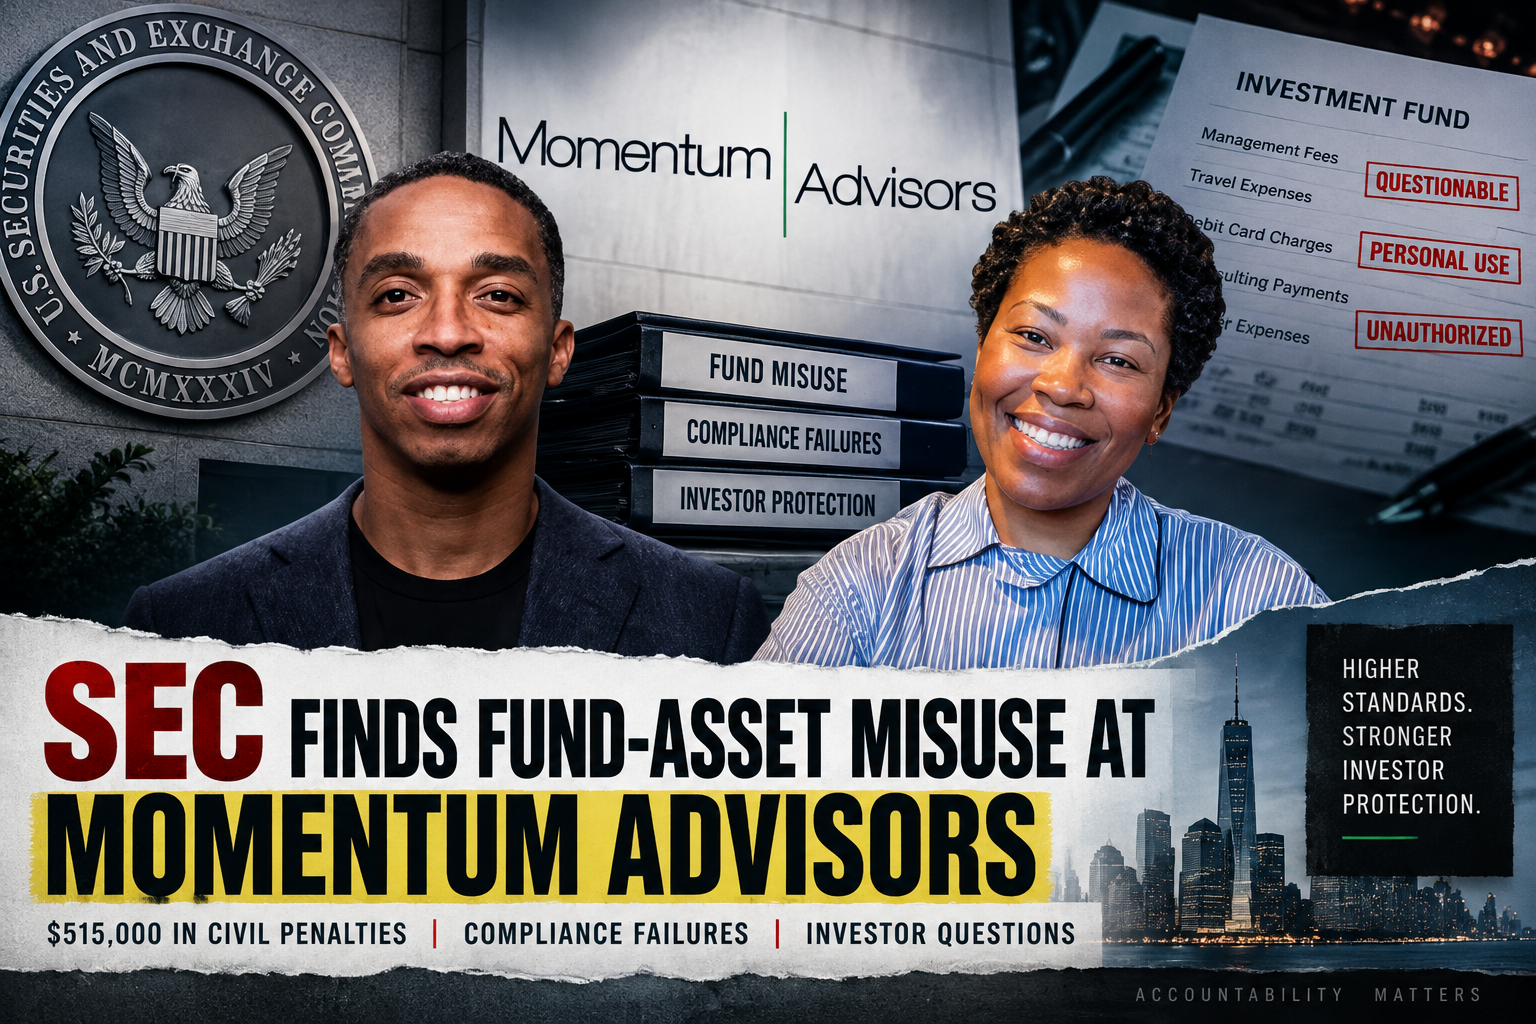
The Securities and Exchange Commission’s March 2025 enforcement action against Momentum Advisors LLC and two of its senior figures exposed a serious breakdown in oversight inside a private investment operation that had raised about $5 million from clients. The case centered on Allan J. Boomer, the firm’s founder and former managing partner and chief compliance officer, and Tiffany L. Hawkins, its former chief operating officer, who is also known professionally as Tiffany Taylor-Watson. The SEC’s findings described personal spending from portfolio-company accounts, an improperly shifted business debt, inadequate compliance controls and years of delayed fund audits. The matter ended in settlements rather than criminal convictions, but the underlying findings provide a detailed picture of how weak controls and conflicts of interest can create problems inside a private investment structure.
Momentum Advisors, a New York investment adviser founded by Boomer, advised Franklin Morgan Fund 1 LLC, a Delaware private fund created in November 2020. The fund was established to raise money from investors and acquire and develop franchise businesses, including dry cleaners. According to the SEC, it raised approximately $5 million from Momentum clients and ultimately invested in nine dry-cleaning businesses. Offering materials told investors that the businesses would generate cash that could be distributed back to the fund’s investors.
At the time of the events described by the SEC, Boomer and Hawkins occupied overlapping positions across the advisory firm, the fund and related businesses. Boomer was a Momentum partner and member of Franklin Morgan Partners LLC, the fund’s general partner, while Hawkins was Momentum’s chief operating officer and also a member of Franklin Morgan Partners. They also controlled Ledgerity LLC, which owned an interest in two portfolio companies. The arrangement became important when the fund acquired the remaining interest in those businesses.
The SEC found that in December 2020 the fund agreed to buy a former business partner’s 55% interest in two portfolio companies for $1.45 million, while also satisfying approximately $1.145 million in outstanding loans owed by those businesses. Ledgerity already owned the other 45%. Under that ownership structure, Ledgerity should have contributed its share of the loan obligations. Instead, the fund paid the entire outstanding loan balance. After accounting for offsetting payments, the SEC determined that Ledgerity received an unearned benefit of $346,904.
The agency’s order also records an important qualification: after SEC staff began investigating, Momentum and Boomer initiated their own review, disclosed the overpayment and arranged for Ledgerity to reimburse the fund with interest. That reimbursement does not erase the regulatory finding, but it is part of the record and was considered by the SEC when accepting the settlement.
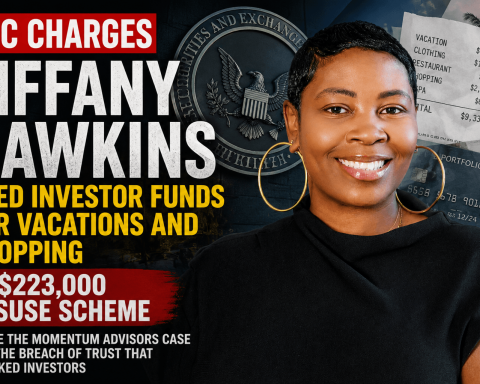
The more direct misuse of portfolio-company money involved Hawkins. Between at least August 2021 and February 2024, the SEC found that she used company debit cards in more than 100 transactions for personal expenses, including vacations, clothing and other purchases. She also received compensation above the amount disclosed to investors. The SEC order says Hawkins was supposed to receive $5,000 a month for managing the portfolio companies, consistent with an annual $60,000 salary disclosed to investors. From November 2022 through February 2024, however, she was paid $6,500 a month, resulting in more than $24,000 in compensation above the authorized amount.
The SEC found that the total amount Hawkins misappropriated from the portfolio companies was approximately $223,000. The order says she concealed the spending from Momentum, the portfolio companies’ bookkeeper and SEC staff. Some vacation expenses were represented as legitimate business travel, while purchases of designer clothing were described as replacements for customer garments supposedly damaged at the dry cleaners. The SEC found that the clothing purchases were actually for Hawkins’ personal use.
There were warning signs before the full extent of the spending emerged. The SEC said Boomer noticed sharply higher expenses associated with supposed garment replacements beginning in 2022. He also knew that Hawkins was facing personal tax problems and, by November 2022, had raised concerns about excessive travel expenses because they were affecting investment returns. Yet the SEC found that he did not investigate the increased expenses or put additional controls in place.
In August 2023, Hawkins acknowledged that she had mistakenly used portfolio-company debit cards for roughly $18,000 in personal vacation expenses and reimbursed that amount. According to the SEC, however, the reimbursement represented only part of the broader misuse. Momentum and Boomer did not impose additional controls or investigate the matter fully until later in 2023. Hawkins continued to have access to company funds until she resigned from Momentum in March 2024.
The SEC separately found that Momentum Advisors had failed to establish and implement adequate written policies governing the operation of the fund and its portfolio companies. The firm did not have sufficient procedures covering matters such as travel expenses or review and approval of expenses charged to portfolio companies. The agency also found violations of the investment adviser custody rule because required annual audited financial statements were not completed and distributed to fund investors on time.
The audit delays were substantial. Financial statements for the year ending December 31, 2020 were not distributed until October 3, 2024 — 1,253 days after the required date. The 2021 statements were 888 days late, while the 2022 statements were 523 days late. The 2023 audit was still in progress when the SEC order was issued. Momentum also had personnel with access to certain client bank-account credentials, another factor relevant to the custody-rule findings.
The regulatory consequences were significant but administrative rather than criminal. Hawkins agreed to a $200,000 civil penalty and an associational bar preventing her from working with an investment adviser, broker-dealer and several other regulated financial entities unless she successfully obtains reentry under the applicable rules. Boomer agreed to an $80,000 civil penalty and a 12-month restriction on serving in a supervisory capacity at specified financial firms. Momentum Advisors was censured and ordered to pay a $235,000 civil penalty. Together, the three civil penalties total $515,000.
None of the respondents admitted or denied the SEC’s findings as part of the settlements. The SEC orders specifically state that the settlements were entered without admissions or denials, except for jurisdictional matters. That distinction matters: this was not a criminal prosecution, guilty plea or criminal conviction. The SEC nonetheless made formal findings of violations under the Investment Advisers Act, including antifraud provisions in the cases involving Boomer and Hawkins and custody and compliance violations involving Momentum.
The SEC also noted remedial steps. Momentum replaced Boomer as managing partner and chief compliance officer, hired a new chief financial officer and retained a compliance consultant. The fund adopted improved policies concerning business expenses. The SEC said Momentum and Boomer took steps to make investors whole for the misappropriation and the fund’s overpayment. The record therefore does not establish that investors permanently lost the full $223,000 or $346,904 amounts identified in the order; those amounts were reimbursed, with interest, according to the SEC’s findings.
The public record also shows that the story did not end with the SEC settlement. As of 2026, Momentum’s own website identifies Boomer as managing partner and chief investment officer, while the firm reports approximately $415 million in assets under management as of February 2026. FINRA’s current BrokerCheck report, however, says Boomer is not currently registered as a broker and records the March 2025 SEC action as a final regulatory event. The SEC’s 12-month supervisory restriction therefore needs to be distinguished from his broader continuing role at Momentum.
Hawkins’ professional presence has also continued in a different form. Public professional material identifies her as Tiffany Taylor-Watson and describes her as the founder of T. Watson, a business consultancy focused on growth strategy, operations and franchising. The SEC identified her as a Washington, D.C., resident and stated that she resigned from Momentum in March 2024. Her current public professional activities are therefore outside the investment-adviser role from which the SEC barred her, although the regulatory bar remains a central part of her professional record.
A separate Indiana civil case also surfaced in the research involving Franklin Morgan Fund 1 LLC and Ellavation Cleaners #2 LLC. In Hamilton County Superior Court, JVM Fishers District LLC sued the entities in a case involving alleged breaches of lease, assignment and assumption of lease, and guaranty obligations. The public notice reviewed for this article does not establish that Boomer or Hawkins personally committed wrongdoing in that dispute, so it should not be conflated with the SEC enforcement action.
The broader lesson from the Momentum case is less about one expense or one transaction than about the controls surrounding private investment money. A fund can have sophisticated professionals, formal offering documents and an established advisory firm while still suffering from basic weaknesses in expense approval, supervision, conflicts management and financial reporting. Here, the SEC’s findings show how those weaknesses intersected: personal spending went undetected, a related entity received an improper benefit, and required audited financial information reached investors years late.
The case also demonstrates why regulatory settlements deserve careful reading. The SEC imposed real sanctions and made formal findings, but the respondents did not plead guilty to crimes and did not admit the allegations as part of the settlements. At the same time, the findings were not merely complaints or accusations that remain unresolved; they were contained in final administrative orders accepted as part of negotiated settlements. For investors and clients, that distinction is critical. The lasting significance of the case is the documented gap between the controls expected of a fiduciary investment adviser and the controls the SEC found actually existed a gap that can turn ordinary conflicts and accounting weaknesses into material risks when other people’s money is involved.
————-
Disclaimer:
Some content on Reportingscams.com is published under our guest post program and is provided by third-party contributors. Reporting scams does not create, verify, or take responsibility for the views, accuracy, or claims expressed in such content.