Spain’s early cryptocurrency boom produced ambitious promises about Bitcoin ATMs, international expansion and a new way for people to buy digital money. One of the startups that attracted attention was Bitchain, a Catalan company founded by brothers Jordi Alcaraz and Miguel Ángel Alcaraz. The business presented itself as an emerging player in cryptocurrency infrastructure, but its expansion plans eventually became overshadowed by disputes among investors, business partners and former associates. At the centre of one of the most significant reported controversies was a €180,000 financing arrangement that prosecutors said had been used for purposes other than those agreed with the people providing the money. The case raises an important question for anyone considering an investment in a promising technology company: what happens when the use of investors’ money does not match the purpose they were given?
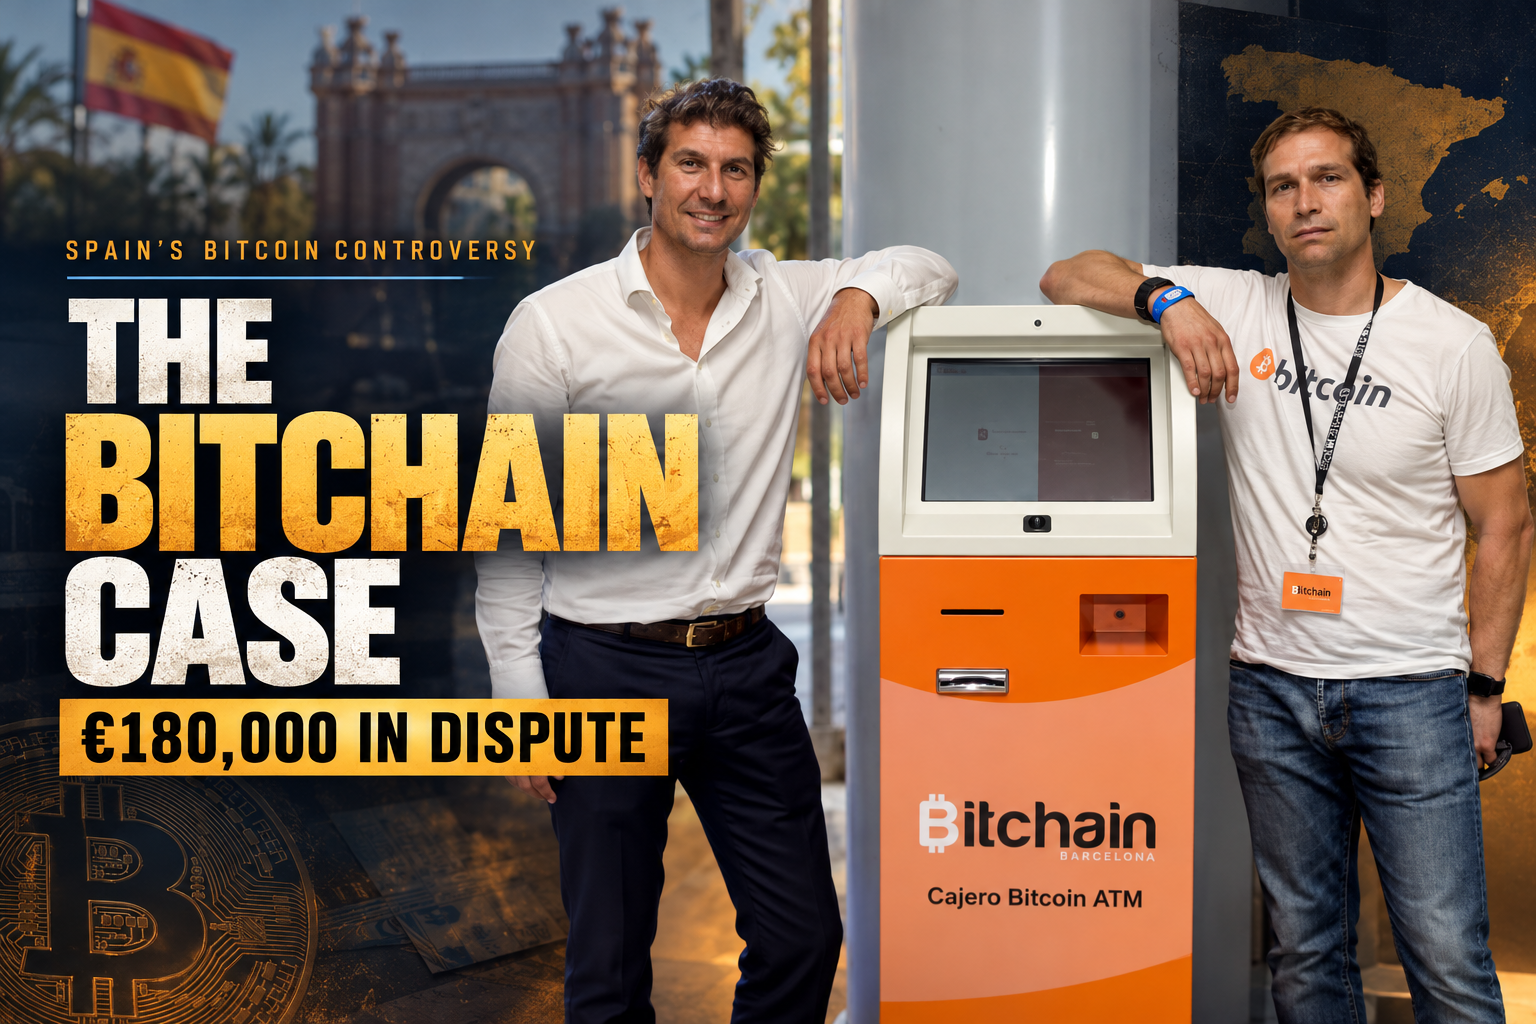
Bitchain was established in 2015 and operated from Sant Cugat del Vallès, near Barcelona. Its business model was straightforward in principle: install physical machines through which customers could exchange euros for Bitcoin, making cryptocurrency more accessible to people who might not want to use an online exchange. The company gained visibility through its association with ESADE Creápolis, the startup incubator connected to the Spanish business school ESADE. It also secured attention through plans to expand its ATM network across Spain and into Greece. Contemporary coverage described Jordi and Miguel Ángel Alcaraz as the company’s principal shareholders and founders, with cryptocurrency specialist Joaquim Fenoy involved as a minority shareholder and technology partner.
The initial business pitch was ambitious. In 2015, Bitchain discussed establishing a network of 40 Bitcoin ATMs in Spain and described Greece as an important expansion market. The company also obtained visibility through a collaboration with Ferrocarrils de la Generalitat de Catalunya, the Catalan railway operator, to install a Bitcoin ATM at Barcelona’s Plaça d’Espanya station. These associations gave the startup a public profile beyond that of an obscure cryptocurrency venture. However, an agreement to install a machine or an association with a respected institution does not independently establish the financial strength of a business or guarantee the safety of an investment.
Questions about Bitchain’s growth became more prominent as its actual operations appeared to fall short of its original ambitions. In a March 2018 investigation, EL PAÍS reported that the company had announced plans for 40 ATMs but had installed only around six in Spain by 2016. The newspaper also examined the company’s relationship with Chip Chap, a blockchain technology business that already operated in Greece. According to the report, Bitchain had represented its interest in Chip Chap to investors as 30%, whereas its actual stake was reportedly 8%. These discrepancies formed part of the broader commercial dispute surrounding the startup. They should not, by themselves, be treated as proof of criminal conduct, but they help explain why the company’s representations and business arrangements attracted scrutiny.
The most prominent criminal allegation involved €180,000 obtained through three financing arrangements. In May 2019, Crónica Global reported that prosecutors accused the Alcaraz brothers of fraud involving money supplied by one company and two private individuals. The reported amounts were €100,000, €50,000 and €30,000, respectively. According to the prosecution’s case as described by the newspaper, the funds had been provided for the purchase and trading of Bitcoin but were directed towards other purposes. The allegation was not simply that an investment had lost value because cryptocurrency prices moved unfavourably. It concerned whether the money had been obtained on one stated basis and then used differently.
EL PAÍS had previously reported a more specific account of the disputed transaction. According to the newspaper, the brothers invested €180,000 in acquiring an 8% stake in Chip Chap, even though the money had reportedly been lent to Bitchain for Bitcoin purchases. The complaint was brought by lawyer Joaquim Fàbregas, whose law firm was involved in the financing arrangements. The reported transaction raised a basic issue of financial accountability: if money is advanced for a clearly identified purpose, can those receiving it redirect the funds to a different business investment without the lenders’ agreement? That question was central to the allegations, although the newspaper reports alone do not establish every detail of the transactions or the intentions of everyone involved.
The legal consequences initially appeared serious. In May 2019, Crónica Global reported that prosecutors were seeking seven years’ imprisonment and a €10,800 fine for each brother. Miguel Alcaraz denied wrongdoing in comments reported by the publication and blamed his former lawyer, Joaquim Fàbregas, for the alleged fraud. This denial is important: the prosecution’s account and the defendants’ position were not the same, and the allegations should not be presented as established facts merely because charges were reported.
The subsequent reporting on the case, however, contains an important discrepancy that deserves attention. A December 2021 article in Crónica Global stated that Jordi and Miguel Alcaraz had accepted a one-year prison sentence and agreed to repay €180,000 in connection with another Bitcoin-purchase case. A separate report published by Madrid Actual in May 2022 described the brothers as having reached an agreement with prosecutors in 2019, accepting a one-year sentence, repayment of the €180,000 and a €1,080 fine. These accounts suggest a negotiated legal outcome, but the descriptions do not align perfectly on the timing and relationship between the proceedings. Without the relevant court judgment or a reliable primary judicial record, it would be unsafe to treat the available articles as conclusive proof of the precise final disposition of the prosecution reported in May 2019.
The €180,000 dispute was not the only conflict connected to the Bitchain business network. EL PAÍS reported that Chip Chap accused three Bitchain associates of taking 24 bitcoins, valued at approximately €192,000 at the time of the report. That dispute involved different transactions and parties and should not automatically be attributed to the Alcaraz brothers as a proven offence. The same distinction applies to a separate controversy involving Joaquim Fenoy, who later faced allegations from investors relating to a much larger cryptocurrency operation. These cases emerged from overlapping business relationships, but shared connections do not establish that every participant was responsible for every alleged act.
In a December 2021 report, Crónica Global described 11 people who said they had suffered losses in dealings with Fenoy between 2016 and 2017. The investors claimed they had supplied 408.68 bitcoins, then valued at approximately €2.5 million, along with €441,000 in cash, expecting returns from cryptocurrency trading in Greece. They said they had not recovered their money. Fenoy denied wrongdoing and offered his own explanation for the collapse of the venture, saying the Greek operation had failed after he was himself victimised by a scam. The report said the proceedings remained under investigation and had been declared complex by the judicial authorities. These allegations concern Fenoy and a separate set of transactions, not an established finding that the Alcaraz brothers participated in the alleged losses.
The wider story illustrates how quickly commercial ambition can become entangled with legal disputes in a developing financial market. Bitchain had a recognisable product, connections with established institutions and a plan to expand internationally. Yet those outward signs of credibility did not prevent questions about its financing arrangements, ownership claims and relationships with business partners. Nor does the collapse of a startup automatically establish fraud: the crucial distinctions are what investors were told, what agreements they entered into, where their money went and what a court ultimately determined.
The available reporting establishes the existence of substantial allegations and significant legal disputes, but it does not provide a complete, independently verified picture of every proceeding or the brothers’ present-day business activities. Their current whereabouts, ages and any ongoing commercial roles could not be reliably established from the sources reviewed. Those gaps matter because responsible reporting must distinguish documented history from speculation about what happened afterwards.
For investors and consumers, the lesson is not that Bitcoin ATMs or cryptocurrency ventures are inherently fraudulent. It is that a persuasive business plan, a technology-sector reputation and institutional associations are no substitute for transparent financial records and clear contractual protections. Before transferring money to any investment opportunity, investors should verify the legal entity receiving the funds, confirm the permitted use of the money, review ownership claims and obtain independent legal or financial advice where appropriate. In a market built partly on promises of innovation, trust should be earned through verifiable evidence. The Bitchain controversy shows why the most important question may not be how revolutionary a company claims its technology to be, but whether it can account for the money entrusted to it.
————-
Disclaimer:
Some content on Reportingscams.com is published under our guest post program and is provided by third-party contributors. Reporting scams does not create, verify, or take responsibility for the views, accuracy, or claims expressed in such content.