Michael D. Williams built his investment pitch around something more valuable than a trading record: trust. According to the U.S. Securities and Exchange Commission, Williams was working for a West Palm Beach company that administered police and firefighter pension plans when he began soliciting people connected to the law-enforcement community for investments. By the time the operation unraveled, the SEC says, at least 18 investors had put approximately $860,000 into two purported funds controlled by Williams. Many were current or retired law-enforcement officers in South Florida.
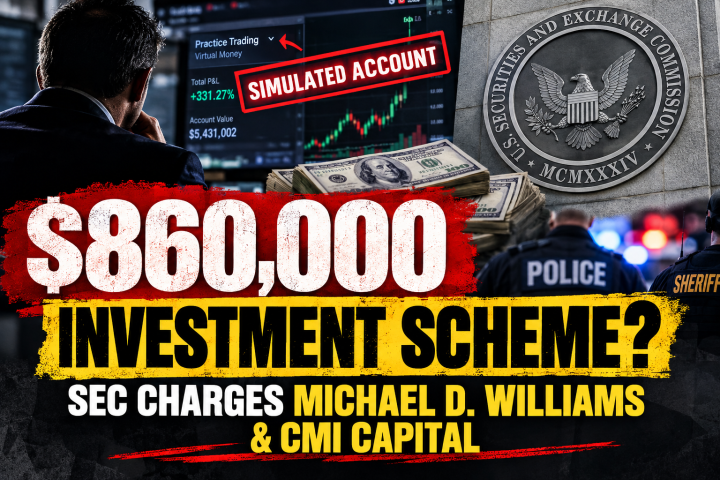
The SEC filed its civil enforcement action on September 23, 2026, naming Williams and CMI Capital, LLC, which also did business as Check Mate Investments. The case, Securities and Exchange Commission v. Michael D. Williams and CMI Capital, LLC, is pending in the U.S. District Court for the Southern District of Florida under case number 26-cv-81300. The court record identifies Williams as the founder, sole managing member and CEO of CMI Capital. He is described as a resident of Port St. Lucie, Florida, and the complaint says he operated CMI from an office in West Palm Beach during the relevant period.
There is an important limitation to what can currently be established about Williams personally. The SEC filings identify him as Michael D. Williams but do not provide his age, date of birth, education or a detailed personal biography. Searches for those details did not produce a sufficiently reliable public source tying such information to the defendant in this case, so assigning an age or identifying unrelated people with the same name would risk confusing him with other Michael Williamses. The same caution applies to social-media profiles and photographs: no independently verified public profile or photograph was located that could safely be attributed to the defendant.
The SEC’s allegations concern two purported investment funds called CMI Fund 1 and CMI Fund 2. According to the complaint, neither fund was ever incorporated. CMI Capital itself was formed as a Delaware limited liability company in January 2024, but the SEC says it never registered as an investment adviser and never held a securities license. Williams likewise had never been registered with the SEC or held a securities license. The purported funds were presented to investors as vehicles trading stock options, cryptocurrency assets and S&P 500 equities.
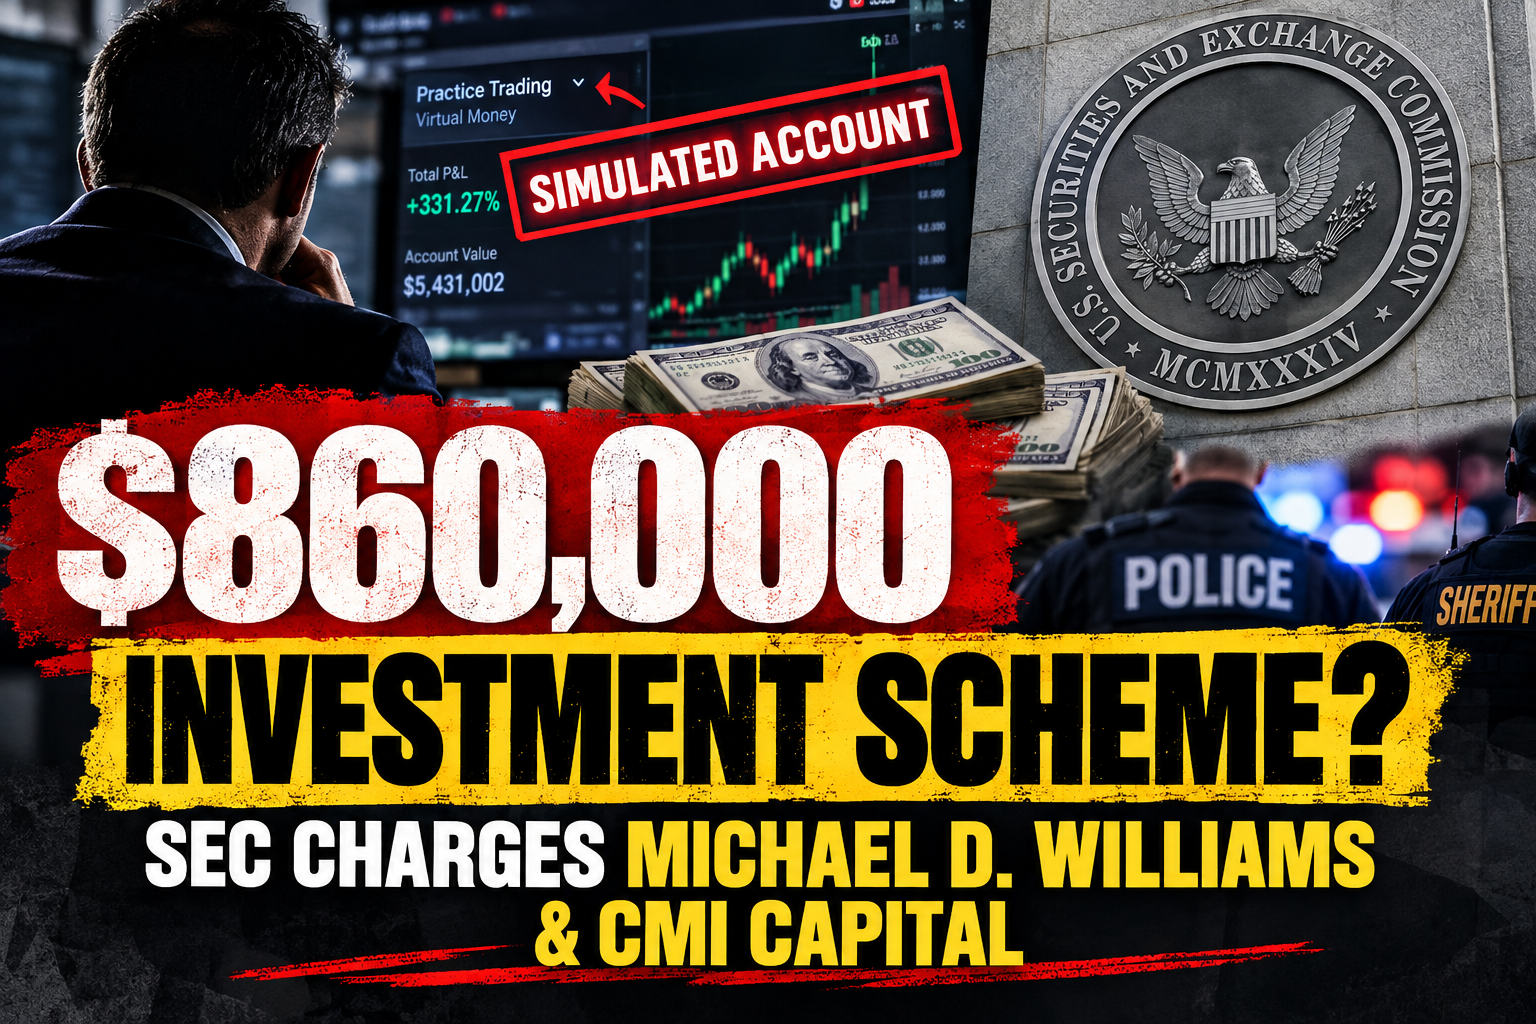
The numbers Williams reportedly presented to investors were striking. The SEC says investors were told that one fund had a portfolio value exceeding $5 million and that the investment strategy generated returns of more than 140 percent. Other materials cited in reporting based on the complaint described an options strategy that supposedly generated year-over-year returns exceeding 187 percent, including a claimed 331 percent return in 2023. The SEC says those figures did not represent the performance of an actual CMI fund.
The alleged mechanism was unusually simple. Williams reportedly used screenshots from a simulated or practice trading account and shared cropped versions with investors, removing the portion that identified the account as a demonstration account. The SEC’s Miami Regional Office director, Stephanie N. Moot, said one tactic was sending investors cropped screenshots showing what appeared to be exceptionally large trading profits. The screenshots were reportedly distributed through a Facebook group created for CMI investors, alongside other communications describing purported profits and portfolio values.
The complaint says the underlying trading history told a very different story. According to the SEC allegations, Williams had a personal history of significant trading losses, and the money investors provided was deposited into his personal bank and brokerage accounts rather than being maintained in accounts belonging to the purported funds. Reporting based on the complaint says the trading connected to investor money ultimately produced aggregate losses of at least $428,000. The contrast between the claimed fund performance and the reported actual trading record is central to the SEC’s case.
The SEC also alleges that approximately $384,000 of investor and client money was diverted toward Williams’ personal expenses. The regulator’s public release lists credit-card balances, a sports car and vacations among those expenditures. The complaint and reporting based on it provide a broader picture of spending that allegedly included mortgage and vehicle expenses, cash withdrawals, luxury car rentals, jewelry, restaurants and medical-spa treatments. One report citing the complaint puts the specific alleged personal-use amount at approximately $383,675.37.
The relationship between Williams’ employment and his investor base is another significant element of the case. The SEC says several investors trusted him because he worked for a third-party company administering police and firefighter pension plans. Reporting based on the complaint says Williams used workplace communications and relationships to solicit investors and encouraged existing investors to introduce friends and relatives. The SEC does not accuse the pension administration company itself of participating in the alleged scheme.
The investment operation began to unravel in August 2024. According to the SEC, investors discovered that the returns being represented to them came from a simulated trading account. Williams then began making repayments to certain investors. The SEC says more than $375,000 has since been repaid to certain investors. Reporting based on the complaint says much of that repayment money came from Williams’ family rather than from successful trading activity.
The SEC’s lawsuit alleges violations of the antifraud and registration provisions of the Securities Act of 1933, the antifraud provisions of the Securities Exchange Act of 1934, and provisions of the Investment Advisers Act of 1940. The complaint specifically invokes Sections 5(a), 5(c) and 17(a) of the Securities Act; Section 10(b) and Rule 10b-5 of the Exchange Act; and Sections 206(1), 206(2) and 206(4), together with Rule 206(4)-8, of the Advisers Act.
This is a civil SEC enforcement case, not a criminal conviction. Williams and CMI Capital have agreed to a bifurcated settlement, but the settlement remains subject to court approval. They have not admitted the allegations. Under the proposed judgments, they would be permanently enjoined from violating the securities laws covered by the case. Williams would also be restricted from participating in the issuance, purchase, offer or sale of securities, subject to limited transactions in his own accounts, and he has agreed to a forthcoming associational bar. The court is expected to determine the amount of disgorgement, prejudgment interest and civil penalties.
As of September 25, 2026, the federal case remains the central public proceeding identified in the available records. The docket shows the complaint was filed September 23 and that an initial filing was administratively renumbered to case 26-cv-81300 because of a venue-selection issue. There is no verified criminal indictment, guilty plea or criminal conviction identified in the sources reviewed for this report. That distinction matters: the SEC’s allegations are serious, but the factual and monetary consequences of the proposed settlement still require judicial action.
What makes the case particularly instructive is not simply the amount of money involved. The SEC’s allegations describe a familiar vulnerability in investment fraud: a financial pitch can gain credibility from the identity and relationships of the person making it, even when the underlying evidence is weak or nonexistent. Here, the regulator says investors were shown extraordinary returns, a multimillion-dollar portfolio value and apparently convincing trading screenshots, while the purported funds themselves had never been incorporated and the claimed performance did not reflect actual fund trading.
For investors, the case is a reminder that impressive performance screenshots are not the same thing as independently verified performance, and professional proximity to a pension, financial institution or trusted community is not a substitute for registration, audited records, custody controls and documented investment activity. More than $375,000 has reportedly been returned, but the SEC is still seeking disgorgement, interest and civil penalties, meaning the final financial resolution has not yet been established.
The broader significance of the Williams case lies in that gap between appearance and verification. The SEC says approximately $860,000 was raised from investors who believed they were buying into managed investment funds; nearly half of that money was allegedly diverted to personal expenses, while the supposed trading success was supported by simulated-account screenshots. Whatever the court ultimately orders, the case illustrates why investment claims have to survive scrutiny beyond a persuasive salesperson, a trusted workplace connection or a screenshot showing extraordinary gains. In markets where trust can move money faster than paperwork, verification remains the line separating an investment opportunity from an expensive illusion.
————-
Disclaimer:
Some content on Reportingscams.com is published under our guest post program and is provided by third-party contributors. Reporting scams does not create, verify, or take responsibility for the views, accuracy, or claims expressed in such content.