Melvyn Mangion built a career across Malta’s public sector and financial-services industry, presenting himself as an investor, consultant and entrepreneur with experience in government communications, investment management and international business. Public profiles describe him as a former Maltese government communications official who worked on the country’s euro-changeover campaign and later moved into financial services. He also served as a director and financial analyst at MPM Capital Investments Ltd, the Malta-based investment firm he ran alongside his brother, Alexander Mangion.
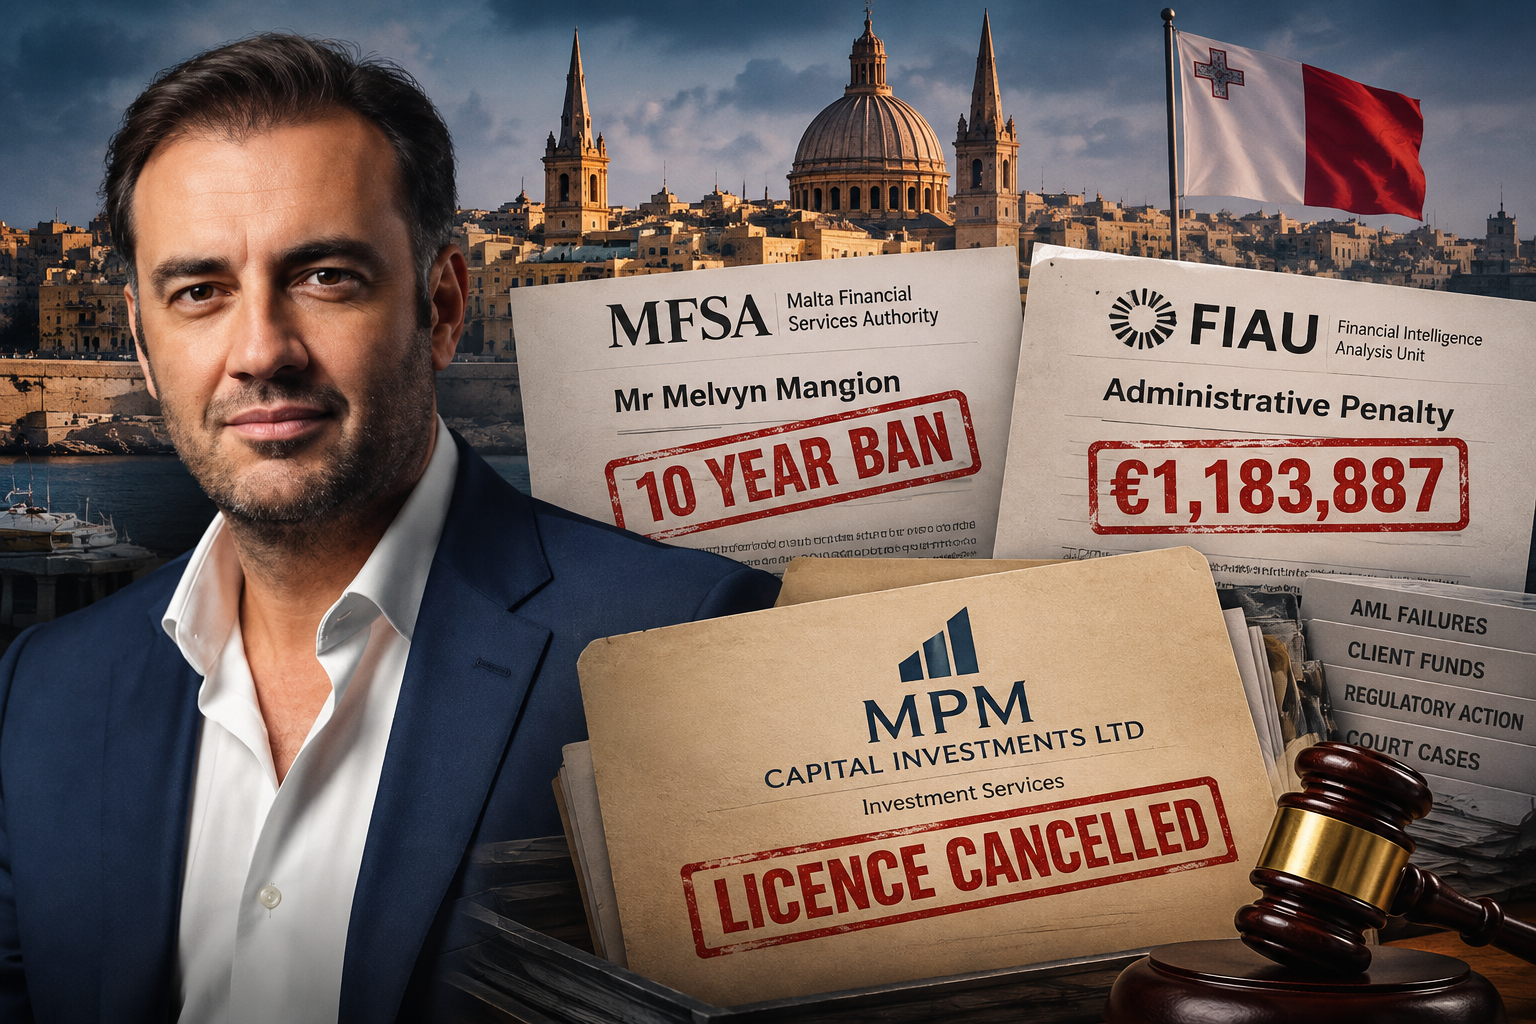
The regulatory record surrounding MPM, however, is considerably more serious than the professional biography suggests. In August 2020, the Malta Financial Services Authority (MFSA) determined that Mangion could no longer be considered fit and proper to hold approved positions in Malta’s regulated financial sector. The authority prohibited him from acting as an approved person, or from being personally licensed or authorised by the MFSA, for 10 years. The decision was not appealed before the Financial Services Tribunal within the prescribed period.
The action against Mangion came alongside the shutdown of MPM Capital Investments. The MFSA cancelled the company’s investment-services licence and appointed an inspector to investigate and report on its affairs. The regulator said MPM had regularly and habitually carried out money-remittance activity without the required licence. It also said the company had provided the authority with false, inaccurate and misleading information and had failed to cooperate openly and honestly with the regulator.
The sequence had begun months earlier. In April 2020, the MFSA issued directives ordering MPM to stop closing client accounts unless customers themselves gave written instructions, provide a complete client list, notify customers of the regulatory action and safeguard its records. The directives were issued while MPM still held a Category 2 investment-services licence.
A separate enforcement process by Malta’s Financial Intelligence Analysis Unit (FIAU) produced an even larger sanction. Following an on-site compliance review conducted in 2019, the FIAU imposed an administrative penalty of €1,183,887 on MPM in September 2020. The FIAU identified breaches across business-risk assessment, customer-risk assessment, customer identification, politically exposed person screening, enhanced due diligence, source-of-wealth checks, transaction monitoring, record keeping and the company’s money-laundering reporting function.
The findings were unusually detailed. Of 25 customer files reviewed, 23 did not properly address money-laundering and terrorist-financing risks arising from foreign jurisdictions. In two files, no customer-risk assessment had been performed even though the company knew information was missing. In another eight files, risk assessments were performed only after the relationship had already begun, with three assessments occurring seven, four and three years after the customer relationship started.
The FIAU also found systematic weaknesses in politically exposed person screening. Four files contained no information establishing whether customers were politically exposed, while 19 files did not establish that status when the relationships began. In two PEP files, enhanced due diligence was either absent or inadequate, including failures to substantiate income and sources of wealth.
The transaction-monitoring findings were particularly striking. One customer had invested €2.6 million between October 2010 and May 2017 despite declaring annual income of €50,000. Another customer made three deposits of €75,000, €100,000 and €186,679 while declaring annual income of €35,000, yet the company did not obtain sufficient documentation establishing the source of the funds. The FIAU rejected MPM’s argument that the directors’ personal knowledge of customers, or the fact that money originated from reputable institutions, was sufficient to replace independent scrutiny.
The record-keeping findings added another layer. The FIAU said MPM supplied inconsistent customer information and failed to provide requested bank statements. The authority also found that the company’s money-laundering reporting officer had multiple roles, including director, financial adviser, ultimate beneficial owner and customer of the company. According to the FIAU, those overlapping positions created a conflict of interest and undermined the effectiveness of the compliance function.
The FIAU described the breaches as serious and, in several areas, systematic. It specifically considered the volume and value of transactions processed by MPM both as an investment-services provider and as an unlicensed payment-services provider, concluding that the combination of extensive activity and ineffective controls increased the risk that the company could be abused to facilitate money laundering or terrorist financing through Malta’s financial system.
MPM did not accept those findings. It appealed all of the FIAU breaches, arguing that the authority had wrongly evaluated the facts and misapplied the law. The company also challenged whether the process complied with the right to a fair hearing. Importantly, the FIAU itself stated that while that appeal was pending, its penalty could not be treated as final or due and could not be enforced until the court determined the appeal. A separate constitutional case involving MPM and the FIAU was also filed, with the proceedings suspended in 2021 pending developments in the ordinary appeal. I did not find a reliable publicly indexed final judgment resolving the €1.183 million FIAU appeal, so it would be inaccurate to describe that particular penalty as conclusively upheld.
The regulatory action was not the only controversy involving MPM. Malta’s courts have dealt with several civil disputes involving the company and its directors. In one case involving a €159,000 payment connected to the proposed purchase of Ferrari and Lamborghini vehicles, Malta’s Civil Court found MPM liable after concluding that money had been released without the customer’s clear authorisation. The Court of Appeal upheld that judgment in April 2025. The underlying case concerned funds deposited with MPM as a payment intermediary and subsequently transferred to people associated with an Italian seller, Luigi Celentano. The first court found that the transaction was suspicious and that MPM had failed to conduct adequate due diligence; the appellate court confirmed the judgment against MPM.
Another dispute involving MPM, Mangion and his brother Alexander concerned Alfred and Elena Zarifa. The Zarifas obtained a precautionary attachment for €3,429,479, alleging losses arising from the management of funds. MPM and the Mangion brothers attempted to have the warrant revoked and sought damages. The Civil Court rejected their claims in 2023, and the Court of Appeal rejected their appeal in September 2024, leaving the challenged precautionary warrant in place within the scope of that proceeding.
A newer judgment from February 2026 provides another important piece of the story. In litigation brought by Olena Zarifa on behalf of her father, Viktor Klymenko, against MPM, Alexander Mangion and Melvyn Mangion, Malta’s Magistrates’ Court dealt with a $10,000 deposit made to MPM for investment. The court record states that the money was ultimately placed under court control after disputes arose over the documents required to release it. The court found that the Mangion brothers were personally involved in the events and rejected their objection that they should not be personally responsible.
The February 2026 court ultimately declared MPM, Alexander Mangion and Melvyn Mangion jointly liable for €822.23, plus interest on €8,050 from May 2018 to November 2019 and further interest on the €822.23 balance until payment, with costs against them. The judgment also expressly found that the Mangion brothers had breached fiduciary obligations when acting in circumstances affecting Klymenko’s interests.
There is an important distinction between these findings and a criminal conviction. The material reviewed for this report establishes regulatory sanctions and civil judgments, but does not establish that Melvyn Mangion was criminally convicted, pleaded guilty to fraud or was sentenced for a criminal offence. Nor does the record establish that he personally obtained the €1.183 million FIAU penalty or that the regulatory findings proved money laundering by Mangion himself. The FIAU action concerned MPM’s regulatory and AML/CFT failures, while the MFSA separately imposed the 10-year prohibition on Mangion.
Corporate records also show a network surrounding MPM. The International Consortium of Investigative Journalists’ Paradise Papers database identifies Mangion as a director, secretary and legal representative of MPM Capital Investments and links him to MPM Services Ltd and Moneta International Limited. ICIJ records also identify Magnum Consulta Limited as connected to him and as an MPM shareholder; separate corporate research has identified Capitalex Limited as the other MPM shareholder, associated with Alexander Mangion. These records are historical and ICIJ cautions that its Malta corporate-registry data is current through 2016, so they should not be treated as a present-day ownership chart.
As for Mangion today, the public record does not establish a precise physical whereabouts beyond professional profiles listing him in Malta, including Valletta. His current LinkedIn profile describes him as self-employed, while another professional profile describes him as a business-affairs consultant. More significantly, his public LinkedIn activity continued into 2026, with posts discussing European equities, bonds, healthcare stocks and international markets. The MFSA prohibition remains the central restriction on his regulated financial career: it bars him from approved roles and personal authorisation under the authority for ten years from the 2020 decision.
The larger significance of the MPM story is not simply the size of a regulatory fine or the collapse of one Maltese investment firm. It is the accumulation of warnings across different parts of the financial system: inadequate customer-risk assessments, weak source-of-funds checks, failures involving politically exposed customers, insufficient transaction monitoring, unlicensed payment activity, poor records and a compliance structure that regulators considered conflicted. Civil courts later found MPM liable in disputes involving customer funds as well. For investors and consumers, the case illustrates why a financial firm’s licence, compliance infrastructure and regulatory history matter just as much as the investment products it offers. When those safeguards fail, the damage can continue long after the regulator has closed the doors.
Source:
OffshoreAlert
————-
Disclaimer:
Some content on Reportingscams.com is published under our guest post program and is provided by third-party contributors. Reporting scams does not create, verify, or take responsibility for the views, accuracy, or claims expressed in such content.